
Here’s something most apartment websites won’t tell you: the denial you got last week might have had nothing to do with your credit score. We’ve seen renters with 650 scores get rejected and someone with a 520 get approved down the street. The difference? Knowing which communities work with your situation, and which ones are just collecting your application fee.
If you’re searching for second chance apartments in Austin, you’ve likely already burned through $200, $400, maybe more applying to places that were never going to approve you. That’s not your fault. The big listing sites show you everything but tell you nothing about screening criteria. And “case by case basis” is just code for “we don’t want to say no upfront.”
We’re the Austin Apartment Team, led by Ross Quade, a licensed Texas REALTOR® with 20+ years in real estate and 14 years living in Austin. Apartment locating is all we do, and renters who feel like the deck is stacked against them are a big part of our work. We’ve worked with just about every scenario you can think of: evictions, broken leases, bad credit, felonies, and every combination in between. We’ve seen renters approved weeks after an eviction by applying at communities whose criteria fit them.
Let’s be upfront about one thing: if you’re a registered sex offender, we can’t help, and we’d rather say so now than waste your time. For everyone else, keep reading.
This guide covers the screening thresholds we track, the third-party approval process most guides skip, the income verification mistakes that trip people up, and which Austin areas have inventory for your situation. By the end, you’ll know where you stand and what your real options are.
Table of Contents
- What “Second Chance” Actually Means
- The Real Screening Requirements
- Credit Problems? Here’s What Actually Matters
- Evictions and Broken Leases: The Real Impact
- Criminal Background: What Can (and Can’t) Be Helped
- Third-Party Approval: How It Works
- Income Verification: The SNAAPT Trap
- Where to Look: Austin’s Second Chance Market
- Net Effective Rent: What You’ll Actually Pay
- How to Apply (And Not Waste Money)
- Situations We Can’t Help With
- Why Work With an Apartment Locator?
- FAQ
- Ready to Find Your Second Chance Apartment?
What “Second Chance” Actually Means (And Doesn’t Mean)
Quick Answer: Second chance apartments are rental communities with flexible screening criteria. They approve some applicants with credit issues, evictions, broken leases, or criminal backgrounds that would disqualify them elsewhere. They’re not “no requirements” housing. You still have to qualify, just through different paths.
Let’s clear up the biggest misconception right now: “second chance” doesn’t mean “anyone gets approved.” It means the community has set criteria for situations that other properties reject outright.
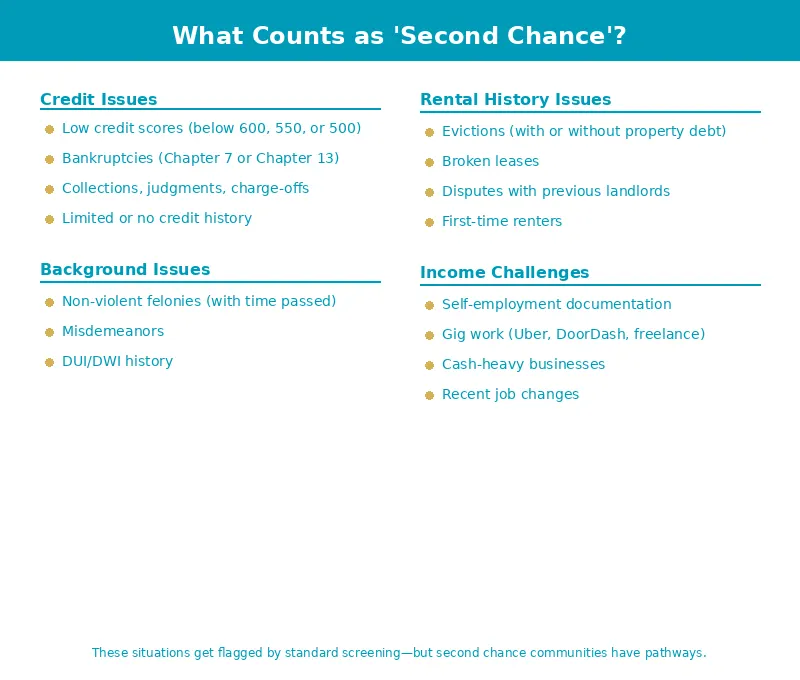
Here’s what counts as a second chance situation:
Credit Issues
- Low credit scores (below 600, 550, or even 500)
- Bankruptcies (Chapter 7 or Chapter 13, open or discharged)
- Collections, judgments, charge offs
- Limited or no credit history
Rental History Issues
- Evictions (with or without property debt)
- Broken leases (with or without property debt)
- Disputes with previous landlords
- Renting for the first time with no history
Background Issues
- Felonies (nonviolent, and some violent ones after enough time has passed)
- Misdemeanors
- DUI/DWI history
Income Challenges
- Self employment with nontraditional paperwork
- Gig work (Uber, DoorDash, freelance)
- Businesses paid mostly in cash
- Recent job changes
The common thread? Standard screening software flags all of these as “high risk,” even when you can pay rent and be a good tenant.
What second chance is NOT:
It’s not a free pass. Every community still has requirements: income verification, an application process, deposits. The difference is that second chance communities have paths to approval that others don’t offer.
It’s not lower quality housing either. Some of the nicest Class A properties in Austin have flexible screening; they just don’t advertise it. Vacancy in Austin sits around 10% (Cushman & Wakefield reported 10.2% in Q3 2025), and even premium communities are working with applicants they would have rejected two years ago.
Here’s what we tell our clients: know your situation, understand your options, and apply with a plan. That’s what the rest of this guide is for.
The Real Screening Requirements (No “Case by Case” Vagueness)
This is where most guides let you down. They say “requirements vary” or “each application is reviewed individually.” That doesn’t help. You need real numbers so you stop wasting money on applications.
Below are the thresholds we track across dozens of Austin communities. Every property makes its own final decision, so none of this is a promise, but these are the criteria that decide whether you have a shot.
Credit Score Thresholds That Actually Matter
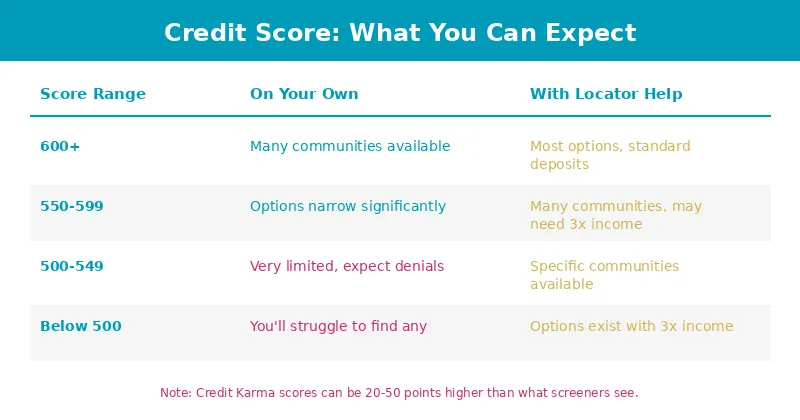
| Credit Score Range | On Your Own | With Our Help |
|---|---|---|
| 600+ | Lots of communities to choose from | Most second chance communities, standard deposits |
| 550-599 | Options narrow a lot | Plenty of communities, may need stronger income |
| 500-549 | Very limited, expect denials | We track communities that screen in this range |
| Below 500 | You’ll struggle to find anything | A few communities, 3x income required |
The difference between searching alone and working with someone who tracks screening criteria? It can be the difference between burning $500 in application fees and getting approved on your first try.
The Credit Karma Warning
This one trips people up all the time: Credit Karma scores can be 20 to 50 points different from what apartment screening companies see, and usually higher.
If Credit Karma says 635, you’re probably looking at 600 or lower in reality. Credit Karma isn’t lying to you. It uses VantageScore, and most apartment screeners use FICO versions. FICO says its scores are used in 90% of lending decisions.
Before you apply anywhere, pull your actual credit report at AnnualCreditReport.com. It’s free, required by federal law, and shows you what screeners will see. Check the “Potentially Negative” section of your Experian report. That’s where property debt hides.
Income Requirements: More Flexible Than You Think
Most renters assume every apartment requires 3x the monthly rent in gross income. That’s the standard, yes. It’s not universal.
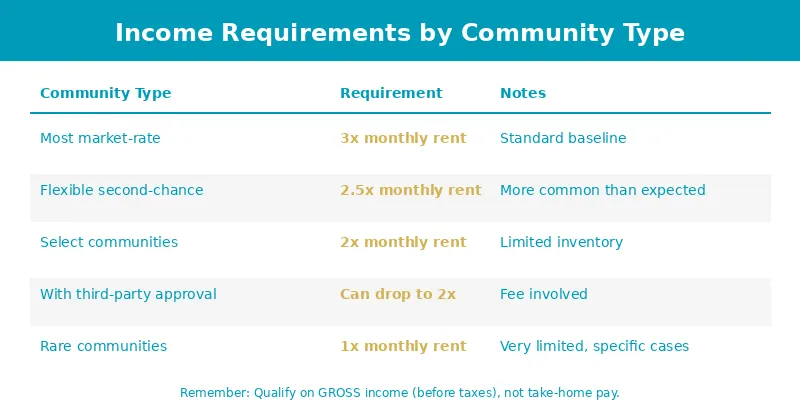
| Community Type | Income Requirement | Notes |
|---|---|---|
| Most market-rate communities | 3x monthly rent | This is the baseline |
| Flexible second chance communities | 2.5x monthly rent | More options than you’d expect |
| Select communities | 2x monthly rent | Limited inventory, often income-restricted |
| With third-party approval | Can drop from 3x to 2x | Fee involved (explained below) |
| Rare communities | 1x monthly rent | Very limited, only in certain situations |
Screening criteria change. Confirm with the leasing office before you apply. A few more things to know:
Gross vs. net income: Apartments qualify you on gross income (before taxes), not take home pay. If your paycheck shows $4,000 gross and you take home $3,200, you qualify based on the $4,000.
Combined household income: Everyone on the lease combines their income. If you make 2x rent and your roommate makes 1.5x, together you hit 3.5x, and you qualify.
Self employed income is “ugly”: That’s the word we use with clients. Gig work, Cash App deposits, Venmo payments: this income is harder to prove. You’ll usually need tax returns or 6 months of bank statements in place of pay stubs. If you have strong credit (650+), some communities we track skip income verification entirely. More on this in the SNAAPT section.
What the Background Check Actually Looks At
Apartment background checks pull three things:
- Criminal history: felonies, misdemeanors, pending charges
- Rental history: previous addresses, eviction records, property debt
- Credit history: score, payment history, collections, bankruptcies
Under the Fair Credit Reporting Act (FCRA), if you’re denied based on background screening, the community has to give you an adverse action notice that says why. That notice tells you what’s flagging your applications.
The screening company (RentGrow, TransUnion SmartMove, and others) isn’t making the approval decision. The property is. The screener hands over data, and the property reads it against its own criteria. That’s why the same background can get approved at one community and denied at another.
Credit Problems? Here’s What Actually Matters
Let’s break down credit issues by type. They’re not all treated the same. A bankruptcy doesn’t hit like medical collections, and property debt is a completely different animal from student loans.
Bankruptcies: Chapter 7 vs. Chapter 13
The first question we ask: is it open or discharged?
Chapter 7 (liquidation): Needs to be discharged (closed). Once it’s discharged, most second chance communities will work with you. It stays on your credit for 7 to 10 years, but communities know a discharged bankruptcy often means you’re starting fresh with no debt.
Chapter 13 (repayment plan): Open is OK. If your payments are current, some communities will work with you during the plan. They want to see the payment history, proof you’re following through.
Here’s a detail most guides miss: the type of debt matters too. A medical bankruptcy or a failed business reads differently than maxed out credit cards. Communities don’t officially separate these, but the story behind the numbers matters when a leasing manager looks at a borderline application.
Collections, Judgments, and “Bad Marks”
Not all negative items are equal. Here’s how apartments usually see them:
Usually not a barrier:
- Medical debt (the three major credit bureaus voluntarily stopped reporting paid medical collections in 2022 and medical collections under $500 in 2023, and many communities now give medical collections little weight)
- Student loans, delinquent or not
- Old collections (5+ years)
- Credit card charge offs
Depends on the community:
- Tax liens
- Recent collections (under 2 years)
- Multiple judgments
Almost always a problem when searching on your own:
- Property debt: This is the big one. Money owed to a previous landlord gets treated very differently from other debt. If you owe a former apartment community $1,500 and it’s sitting in collections, most places will deny you when you apply on your own.
Here’s the good news: property debt is one of the most common situations we work with, and we track communities that accept it at a range of balances. The amount changes which communities fit, not whether you have options.
Limited or No Credit History
Renting for the first time, or arriving without a U.S. credit file, brings a different challenge: there’s nothing to judge. No score, no history, no data.
Your options:
Other paperwork: Some communities will accept 6 months of bank statements showing steady deposits, an employment letter, or proof of assets.
Cosigner: A cosigner (parent, relative, friend) with good credit and enough income can get you approved at most communities. They’re just as responsible for the lease, so everyone needs to understand the commitment.
Programs for new renters: A handful of Austin communities market directly to people renting for the first time. They’re used to applicants without rental history and set their criteria with that in mind.
The good news? No credit is often easier than bad credit. You’re a blank slate, not a risk flag.
Evictions and Broken Leases: The Real Impact on Your Search
This is where we spend most of our time with clients. Evictions and broken leases are the most misunderstood part of rental screening. Most people lump them together. They’re not the same, and the difference matters for your approval odds.
Broken Lease vs. Eviction: Know the Difference
Broken lease: You ended your lease early. Maybe you moved for work, maybe you couldn’t afford rent anymore, maybe you just left. It’s a contract issue: you broke an agreement.
Eviction: A court ordered your removal from the property. There’s a legal judgment against you. It went through the courts.
Both show up on screening reports. Evictions get viewed more seriously since they involve a court. A broken lease says “this person left early.” An eviction says “this person had to be legally removed.”
Here’s the detail: lots of people say “I have an eviction” when they actually have a broken lease. If you left on your own, owing money or not, that’s usually a broken lease, not an eviction. Pull your records and know which one you have.
The Property Debt Factor
This is the variable that changes everything, at least when you’re applying on your own.
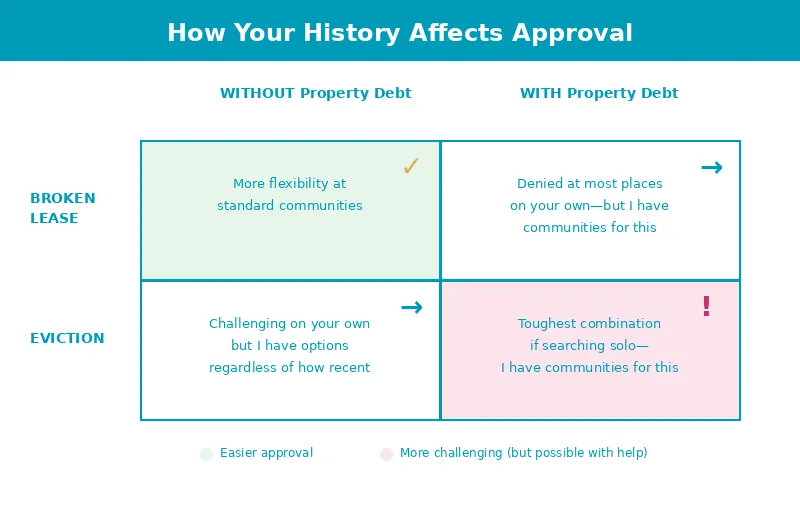
Broken lease WITHOUT property debt: Standard communities have more flexibility here.
Broken lease WITH property debt: If you’re applying on your own, you’ll likely get denied at most places. Some communities we track work with this situation regularly.
Eviction WITHOUT property debt: Hard on your own. We track options for recent and older evictions alike.
Eviction WITH property debt: The toughest combination if you’re searching solo. This is where knowing each community’s criteria matters most. We track communities that accept this combination, including evictions from last month.
Property debt is money you owe a previous landlord: unpaid rent, early termination fees, damages, cleaning charges. It often gets sold to a collection agency, so it might show up under a different company name than your old apartment.
To find it, pull your Experian report and look in the “Potentially Negative” section. The original creditor field should show the apartment community’s name, even after a collection agency buys the debt.
Why We Don’t Give You a Timeline Chart
You’ll see other guides with neat little tables: “Eviction under 2 years = limited options, 2 to 5 years = moderate options,” and so on. We don’t do that. It’s misleading.
Real life is messier. We’ve seen renters approved weeks after an eviction. We’ve seen people with older broken leases struggle over other factors. It comes down to:
- Whether there’s active property debt
- Your current credit score
- Your income stability
- The communities you apply to and who owns them
- What else is on your record
Some locators see “eviction” and send you to the same handful of communities they always use, or tell you to wait a few years. That leaves people without housing when there are options out there.
We work with evictions and broken leases of all ages, with and without property debt, at any balance. The dates and dollar figures matter less than knowing which communities to approach and how to present your application. That’s the difference.
The Payoff Letter Strategy
If you have property debt, paying it off opens up standard communities. There’s a right way and a wrong way to do it.
The process:
- Contact the collection agency (or the original creditor if they still hold the debt)
- Negotiate a settlement; you can often pay less than the full balance
- The step that matters most: get the settlement agreement in writing BEFORE you pay
- Pay the agreed amount
- Request a payoff letter (it usually comes within 24 to 48 hours)
One client in South Austin owed $1,100 in property debt. She called the collection agency, explained her situation, and they agreed to settle for around $550. She paid it, got the payoff letter, and suddenly had access to communities that would have rejected her the day before.
The payoff letter is your proof. It shows the debt is resolved. Lots of communities that won’t touch active property debt will approve you with a payoff letter in hand.
Important: Get that written agreement before paying. We’ve seen people pay a “settlement” and then have the agency call it a partial payment. Protect yourself.
If you can’t pay off the debt right now, don’t assume you’re stuck. Some communities accept active property debt. It comes down to knowing where to apply.
Property Debt Amounts
When you’re searching on your own, the size of your debt affects how many denials you’ll get. With us, the balance changes which communities we target, not whether we can help.
Criminal Background: What Can (and Can’t) Be Helped
Criminal background is the topic nobody wants to talk about in detail. Other guides make vague “felony friendly” claims without saying what that means. Here are the details.
The Good News First: What’s Usually Not a Problem
DUI/DWI: At most communities, this is a nonissue. It shows up on your background, but most of the properties we work with don’t deny for a DUI alone, especially an older one.
Simple possession: Minor drug charges, marijuana charges in particular, get overlooked more and more. Texas hasn’t legalized it, but Austin communities usually take a practical view of old possession charges.
Most misdemeanors: Theft under a certain amount, minor assault charges that were dismissed, trespassing: these rarely sink an application on their own.
Old charges (7+ years): Time matters a lot. Something from a decade ago carries far less weight than something from last year.
Nonviolent Felonies: Timing Is Everything
For felonies without violence (property crimes, white collar offenses, drug possession but not distribution, computer crimes), the key question is how long ago it happened.
Different communities count time differently:
- Some require 7 years from the charge date
- Others require 7 years from the sentencing date (which could be 1 to 2 years after the charge)
- Some require 10 years
- A few require 20+ years
This is where knowing each community’s criteria matters. A felony that’s 8 years from the charge but only 6 years from sentencing might qualify at some places and not others.
Deferred adjudication is better than a conviction. If you finished deferred adjudication successfully, make that clear. It’s not the same as a conviction on your record, and some communities treat it more favorably.
Under 7 years? There are still options. Even with credit issues, we can often find a fit. The biggest factor is steady income: 3x the monthly rent coming in every month. That’s what gives communities the confidence to work with you.
Class A Misdemeanors: The Middle Ground
Class A misdemeanors sit between minor misdemeanors and felonies. They include:
- Assault (depending on circumstances)
- DWI (second offense)
- Evading arrest
- Certain theft charges
For Class A misdemeanors at newer, stricter communities, you’ll usually need:
- A credit score of 600 or above
- Income of 3x monthly rent
- If self employed: tax returns (pay stubs won’t cut it)
Older communities and those with flexible screening may have more room to work with you.
Violent Felonies: It’s About Income
Assault, robbery, domestic violence: these take more targeted placement. The key requirements:
- Credit usually needs to be 600+
- Income of 3x rent is a must: steady income you can prove is the #1 factor
- 7+ years helps, and some communities consider more recent cases too
If you’re searching on your own with a violent felony, you’ll hit a lot of dead ends. We’ve helped people with violent felony backgrounds find housing. It takes knowing which communities to approach, and that’s our job. Steady income is what makes it possible.
What Absolutely Disqualifies
We need to be direct about the situations we can’t help with:
- Sex offenses / registered sex offender: no community we work with will approve this
- Injury to a child: a universal disqualifier
- Injury to an elderly person: a universal disqualifier
Active parole with a violent felony: This one’s not an automatic no, but the requirements are strict. Some communities will work with you, but you’ll need credit above 600 and income of at least 3x the monthly rent. No exceptions on those numbers.
These aren’t “difficult” situations; they’re firm stops. If this is your situation, we’re sorry, but we don’t have a path to offer. We’d rather tell you now than take your time and give you false hope.
Third-Party Approval: How It Actually Works
Most guides mention “case by case” or “conditional approval” and stop there. They never explain how it works. Third-party approval is how lots of people with recent evictions or serious issues actually get into apartments.
What Third-Party Approval Actually Is
Think of it as insurance for the apartment community.
When you apply and the screening flags an issue (a recent eviction, active property debt, several problems at once), the community has a choice. It can deny you outright, or it can offer third-party approval.
A third-party company steps in and takes on the risk. It looks at your situation, sets a fee based on that risk, and if you pay it, the company backs your lease. If you later default, the third-party company covers the community’s losses.
It’s not a loan. You’re not borrowing money. It’s a one time fee that makes you an acceptable risk.
The Complete Process (What Actually Happens)
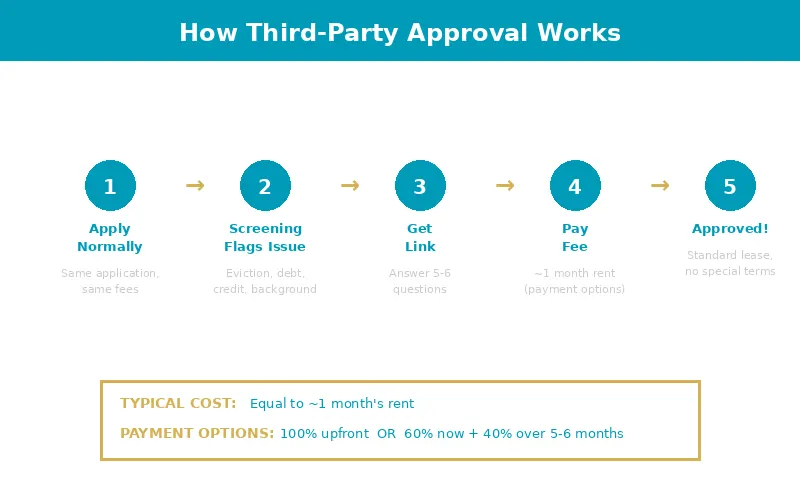
Here’s the step-by-step:
- You apply to the community normally: same application, same fees
- Screening flags your issue: eviction, property debt, credit, background
- The community offers the third-party option: in place of an outright denial
- You get a link: to the third-party service’s portal
- You answer 5 or 6 questions: about your situation, income, and circumstances
- They run a soft credit pull: it doesn’t hurt your score
- You get a fee quote: based on how risky they judge your file
- You pay the fee: options below
- The community hears right away: your lease gets prepared as a standard agreement
Once you pay, your lease is completely normal. No special terms, no ongoing fees, no mark against you.
What It Costs (Real Numbers)
The fee usually equals one month’s rent. If you’re renting a $1,400 apartment, expect around $1,400 for third-party approval.
Payment options:
- 100% upfront: pay it all before move-in
- 60% upfront + 40% spread out: pay 60% now and the other 40% over 5 to 6 months, added to your rent
Some people balk at this cost. That’s fair; it’s a lot of money. Here’s what it buys: approval at a community that would have denied you, no more rounds of application fees at places that might deny you, and housing now instead of waiting years for your record to age.
When Third-Party Makes Sense
Third-party approval is worth it when:
- Your eviction is recent (under 2 years) and you have property debt
- You have several issues that add up to a denial at most places
- You need one particular community for its location, schools, or commute to work
- It really is your best or only option after you’ve checked the alternatives
When to Skip Third-Party
Don’t use third-party approval if:
- Other communities will approve you without it: This is where working with us helps. We’ve had clients ready to pay a $1,500 third-party fee when a community five minutes away had criteria that fit them without it. That’s $1,500 back in their pocket.
- You can pay off property debt for less than the third-party fee
- Your issue is old enough that standard communities will work with you
The key is knowing your options before you commit to the fee. That’s what we help clients figure out.
The Third-Party Companies
The main names you might run into are services like Jetty, Rhino, or a property’s own program. Each community works with its own providers, so you don’t get to shop around. The community tells you which service it uses.
These aren’t scams. They’re legitimate risk services that have become standard in the industry, as communities look for ways to fill units and still manage risk. The National Apartment Association has written about the growth of these services as apartment owners look for flexible screening options.
Income Verification: The SNAAPT Trap (And How to Get Through It)
We’ve watched too many applications get delayed, or denied, over something completely avoidable. Income verification has changed a lot in the past few years, and most renters have no idea what they’re walking into.
What Is SNAAPT?
SNAAPT is an antifraud income verification system that a growing number of Austin apartment communities use. In place of a leasing agent glancing at your pay stub and checking a box, SNAAPT connects directly to your bank account and payroll provider to confirm your income documents are real.
It’s built to catch fake pay stubs, which, yes, people do send. It catches innocent mistakes too, and those can torpedo your application.
The Mistake That Delays Applications
Here’s what happens all the time:
You download your pay stub from your payroll provider. You rename the file from “paystub_123456.pdf” to “John_Smith_Paystub_January.pdf” so it’s easier to find. You upload it to the application.
SNAAPT rejects it.
Why? The system checks the file’s metadata to confirm documents come straight from the source. Rename a PDF, open it and save it again, screenshot it, or do anything other than upload the original file, and SNAAPT flags it as possibly altered.
You didn’t do anything wrong. You were just organizing your files. Now your application is delayed, the leasing office is asking for documents again, and you’re stressed about a unit you wanted.
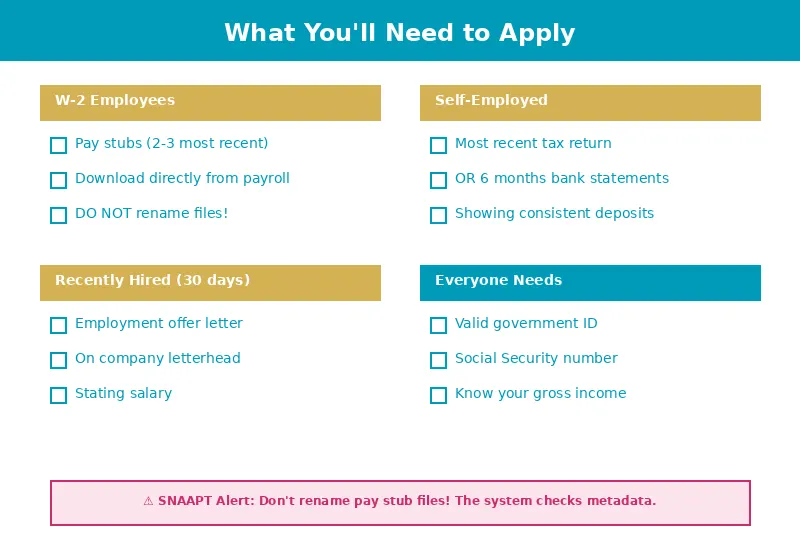
The fix: Download your pay stubs straight from your payroll provider (ADP, Gusto, Paychex, whatever your employer uses). Don’t rename the files. Don’t open them. Upload them exactly as downloaded.
Self Employed and Gig Workers: Your Income Is “Ugly”
We use that word with clients since it fits. If your income comes through Cash App, Venmo, PayPal, or Zelle, apartment communities are going to have a hard time confirming it.
SNAAPT’s connections with these payment apps are, from what we’ve seen, very unreliable. The check fails, the amounts don’t match up, or the system can’t sort the income properly.
What you need instead:
- Tax returns: the gold standard for self employed income. Your most recent return showing your adjusted gross income.
- 6 months of bank statements: showing regular deposits that match your income pattern.
- Employment offer letter: if you were hired in the last 30 days, a formal offer letter on company letterhead stating your salary can work at lots of communities.
The strong credit shortcut: If you’re self employed with good credit (usually 650+), some communities we track don’t verify income at all. They look at your credit history and trust that you’re responsible. That changes the math for freelancers and business owners with solid finances and messy paperwork.
If you’re a gig worker (Uber, DoorDash, Instacart, freelance) without strong credit, start gathering your bank statements now. Don’t wait until you’re applying. Six months of statements with regular deposits gives communities confidence that your income is real and steady.
How to Prepare Before You Apply
Before you send in any application:
- Download fresh pay stubs from your payroll portal; don’t use old downloads
- Don’t change file names or open and save the documents again
- Have bank statements ready as backup, especially with any non W2 income
- Know which communities have stricter verification: we can tell you upfront
The verification systems keep getting smarter. Communities are spending on fraud prevention after getting burned by fake documents. Knowing how the system works keeps you from getting caught in a net meant for actual fraudsters.
Where to Look: Austin’s Second Chance Apartment Market
Now let’s talk geography. Where you look in Austin matters as much as what’s on your record. Some areas have plenty of second chance inventory. Others have almost none.
Why the Current Market Works in Your Favor
Austin’s apartment market looks very different from 2021 and 2022. Back then, vacancy was below 5%, communities had waitlists, and screening criteria were strict since landlords could afford to be picky.
Today? Vacancy hit 10.2% in Q3 2025, according to Cushman & Wakefield. Rents have dropped roughly 5% year-over-year, and Yardi Matrix data shows Austin with the weakest rent performance among major metros. Thousands of new units have opened over the past two years.
What does this mean for you?
Communities that would have rejected your application two years ago are now willing to work with you. They have empty units. Empty units don’t pay the bills. A tenant with an eviction from three years ago who can pay rent today beats an empty unit.
According to CoStar research, roughly 65% of Austin apartment complexes offered some kind of concession in 2025. We’re seeing specials we haven’t seen in years: up to 8 to 12 weeks of free rent, gift cards up to $3,000, waived admin fees, reduced deposits. Specials like these show communities are competing for tenants, including tenants they might have turned away before.
Austin Area Breakdown for Second Chance Renters
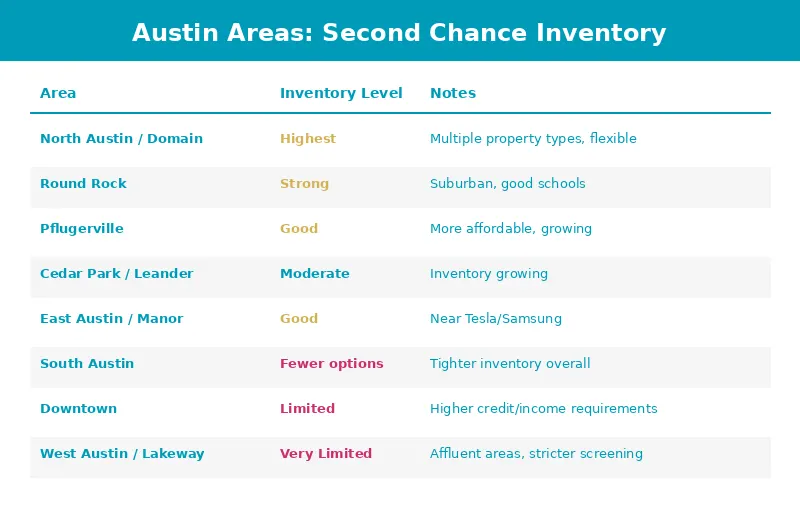
Not every part of Austin has the same second chance inventory. Here’s what we’re seeing:
| Area | Second Chance Inventory | Notes |
|---|---|---|
| North Austin / Domain area | Highest concentration | Lots of property types, newer construction, many flexible communities |
| Round Rock | Strong options | Suburban, an easy I-35 run to Austin, solid second chance inventory |
| Pflugerville | Good coverage | Lower rents than Round Rock, growing inventory |
| Cedar Park / Leander | Moderate options | Inventory growing as the area builds out |
| East Austin / Manor | Good options | Near the Tesla and Samsung plants, newer development |
| South Austin | Fewer options | Tighter inventory overall, but some communities work with second chance renters |
| Downtown | Limited | Higher credit and income requirements at most high rises |
| Kyle / Buda | Some options | Farther out with lower rents, growing |
Where Options Really Are Limited
Here’s where second chance renters will struggle:
West Austin / Lakeway / Westlake: Very few apartments in general, and the ones there tend to screen harder. Rents run high, rental communities are scarce, and there’s less flexibility.
Luxury high rises downtown: The Class A towers with concierge service and rooftop pools usually set higher credit and income thresholds. It’s less about being strict on background issues and more about baseline requirements of 650+ credit and 3x income with no wiggle room. If you meet those numbers, you may have options even with other issues on your record.
Brand new lease ups: This one surprises people. You’d think new communities trying to fill units would be flexible. Sometimes they are. Lots of new properties start with strict criteria and only loosen up later if leasing is slow. It’s worth asking, but don’t assume.
The Geographic Strategy
If you’re flexible on where you live, here’s our advice:
Start your search in North Austin, Round Rock, and Pflugerville. These areas have the most communities we work with that offer flexible screening. You’ll have more options to compare, a better position to negotiate specials, and higher odds of approval.
Expand to East Austin and Cedar Park/Leander if you need to be closer to a certain employer or have other location needs.
Save South Austin and Downtown for when you have to be there. Inventory is tighter, and Downtown’s higher credit and income thresholds make it hard for some situations.
This isn’t about where’s “better” to live. It’s about where your odds of approval are highest for your situation. And honestly, this is where working with us saves you weeks of frustration: we track the screening criteria at communities in each of these areas.
Net Effective Rent: What You’ll Actually Pay
With all the specials out there right now, sticker price tells you very little. What matters is what you’ll actually pay over your lease. That’s called net effective rent, and knowing it can save you hundreds of dollars, or show you that a “more expensive” apartment is actually cheaper.
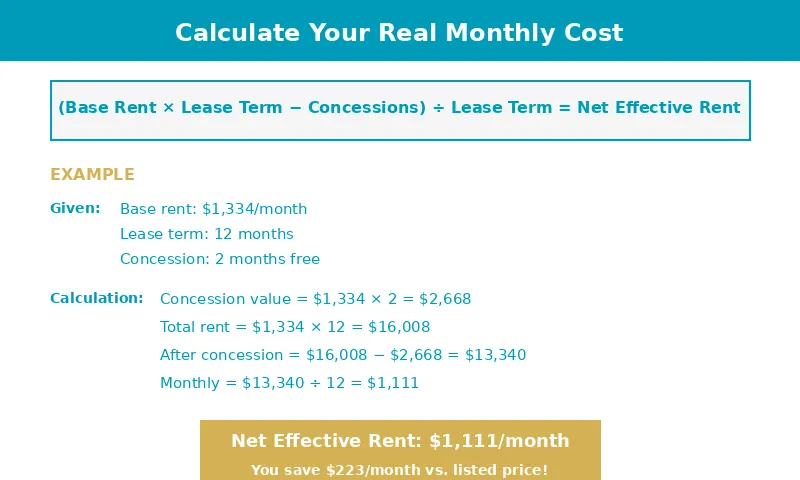
The Formula
Real Example
Let’s say you’re looking at an apartment listed at $1,334/month. The community is offering 2 months free on a 12 month lease.
Here’s the math:
- Base rent: $1,334
- Lease term: 12 months
- Concessions: $1,334 x 2 = $2,668
Calculation: ($1,334 x 12 - $2,668) / 12 = $1,111 net effective rent
That’s $222 less per month than the listed price. Over the full lease, you save $2,668.
Why This Matters for Second Chance Renters
You might face a higher deposit over your credit or rental history. That stings upfront. If the community is offering 6 to 8 weeks of free rent, the math often works out in your favor over the lease.
We run these numbers with every client. It changes how you compare options. A $1,400 apartment with 2 months free beats a $1,300 apartment with no special.
What to Look For Right Now
- Free rent: the biggest savings; look for 6 to 12 weeks free
- Gift cards: some communities offer $500 to $3,000 gift cards at move-in
- Reduced deposits: worth asking for if your deposit would otherwise be high
- Waived fees: application fees, admin fees, amenity fees
How to Apply (And Not Waste Money)
Application fees add up fast. We’ve talked to people who spent $500, $800, even over $1,000 applying to places that were never going to approve them. Here’s how to avoid that.
Before You Apply: Know Your Situation
Pull your credit report at AnnualCreditReport.com before you do anything else. Check the “Potentially Negative” section on Experian for property debt. Know your exact gross income (gross, not take home). And be honest with yourself about any background issues.
The more clearly you understand your situation, the better we can match you with communities whose criteria fit it. Less guessing, fewer wasted fees.
What Documents You’ll Need
W-2 employees:
- Pay stubs (downloaded straight from your payroll provider; don’t rename the files)
- Usually your 2 or 3 most recent stubs
Self employed:
- Your most recent tax return, or
- 6 months of bank statements showing regular deposits
Recently hired (within 30 days):
- An employment offer letter on company letterhead stating your salary
Everyone:
- Valid government ID
- Social Security number
Timing: You Don’t Need to Apply on the Spot
Some people think they have to fill out an application during their tour. You don’t. Most communities give you 24 to 48 hours to apply and still hold the pricing and specials you discussed.
Take that time. Get your documents ready. Apply when you’re prepared, not when you’re pressured.
The Honesty Rule
We tell every client the same thing: if you lie, they will deny.
Undisclosed issues (an eviction you didn’t mention, a felony you hoped wouldn’t show up, income you stretched) lead to an automatic denial. You lose your application fee, your admin fee, and your shot at that unit.
Tell us everything upfront. We’ve heard it all. Nothing you tell us will shock us, and knowing your full situation lets us point you toward communities whose criteria fit it.
Let’s Be Honest: Situations We Can’t Help With
We’d rather be upfront about our limits than waste your time.
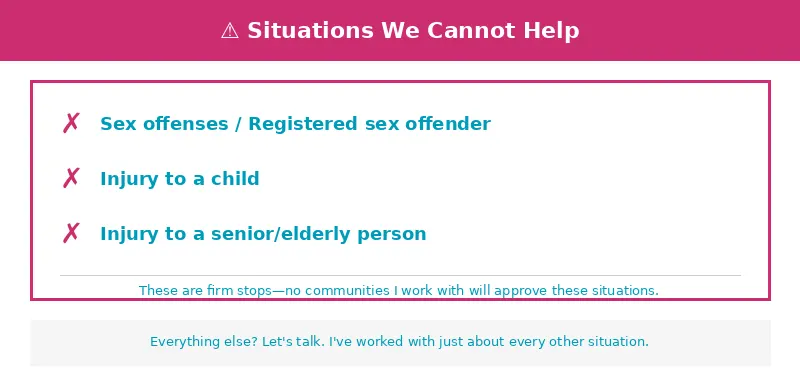
Absolute Disqualifiers
These are the situations where we don’t have a path to offer:
- Sex offenses / registered sex offender
- Injury to a child
- Injury to an elderly person
If this is your situation, we’re truly sorry. We wish we had options for you, but we don’t.
Why We’re Telling You This
We want you to be honest with us about your situation. The more you tell us, the better we can match you with communities whose criteria fit. We’re not here to judge. We’re here to find you housing.
The only true stops are sex offenses and injury to a child or an elderly person. Everything else? Let’s talk. You’ll need to show 3x the monthly rent in income (or an offer letter if you’re starting a new job), and with that in place, we can work with just about any combination of issues.
Why Work With an Apartment Locator? (And How We Get Paid)
Fair question. Here’s how the model works.
Everyone Comes Out Ahead
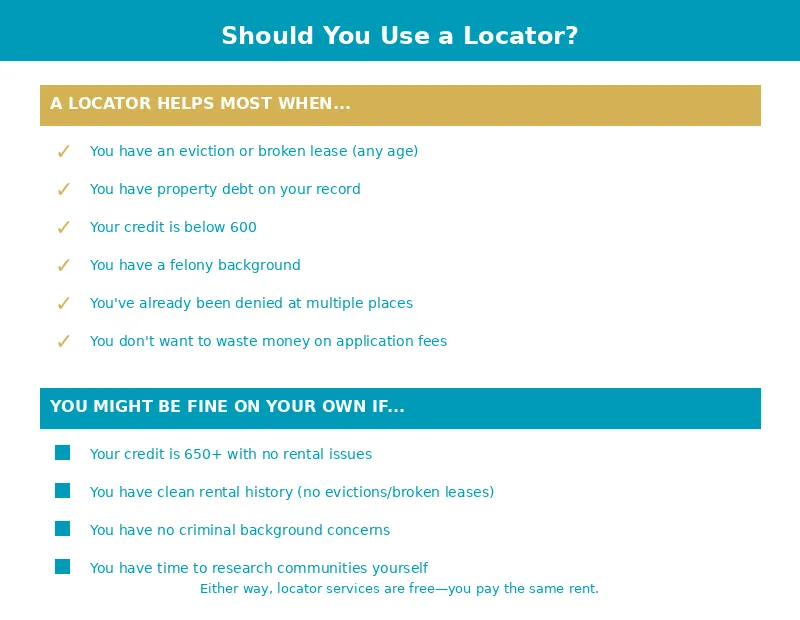
- You win: free research, a short list of communities whose screening criteria fit your situation, someone in your corner during the application, and someone who tracks screening criteria so you stop wasting money on applications
- The community wins: it gets a qualified tenant it might have missed
- We win: we get a referral fee from the community’s marketing budget
The Key Point: Your Rent Is the Same
Use a locator or find the apartment yourself; your rent is identical. The community pays our fee out of its marketing budget, the same budget it spends on Apartments.com ads or Google clicks. You don’t pay more. There’s no markup.
What You Actually Get
- Screening knowledge: we track which communities’ criteria fit your situation before you apply
- Fewer wasted fees: no more $50 to $100 application fees at places that were going to deny you
- Negotiation: we’re happy to ask for better specials, reduced deposits, or waived fees (most clients don’t think to negotiate)
- Someone in your corner: if your application hits a snag, we call the leasing office to work it out
- Help after you sign: questions after move-in? We’re still here
Licensed and Regulated
Our team is led by Ross Quade, licensed through the Texas Real Estate Commission (TREC). In Texas, apartment locating for a fee requires a real estate license. This isn’t a side hustle or a referral scheme. It’s a regulated profession with professional standards and accountability.
Frequently Asked Questions
What credit score do I need for a second chance apartment in Austin?
We work with all credit scores. The communities that fit you change with your score. 600+ opens the most doors, but there are options for 550 to 600, 500 to 550, and even below 500. Strong income (3x rent) helps, and we can work with property debt at any credit level. The score is just one factor.
Can I get approved with an eviction on my record?
Yes, it’s possible. We work with evictions of all ages, recent or old. Whether you have active property debt from that eviction matters, and we track communities for both situations. Some locators will tell you to wait. You don’t have to.
How much does third-party approval cost?
Usually one month’s rent. You can pay 100% upfront, or about 60% upfront with the other 40% spread over 5 to 6 months. It’s a one time fee. Once it’s paid, your lease is completely standard.
What income do I need to qualify?
Most communities require 3x the monthly rent in gross household income. Some accept 2.5x or 2x. With third-party approval, a 3x requirement can sometimes drop to 2x, and we can go over that before you tour and apply so you have the right numbers. All applicants’ incomes combine, so roommates or partners count together.
Are apartment locators really free?
Yes. The apartment community pays us a referral fee from its marketing budget. Your rent is exactly the same whether you use us or not. There’s no catch.
What if I have both bad credit AND a broken lease?
Several issues at once don’t wipe out your options. They just mean you need to know exactly where to apply. Search on your own and you’ll waste a lot of money on application fees at places that were never going to approve you. The key factors: how recent the issues are, whether there’s active property debt, and what your current income is. This is where working with someone who tracks each community’s criteria helps. We can tell you upfront which places take your combination, so you’re not throwing money away.
What’s the difference between an eviction and a broken lease?
A broken lease means you ended your lease early, a contract issue. An eviction is a court ordered removal, a legal judgment. Both show on screening reports, but evictions usually get viewed more seriously. Lots of people think they have an eviction when they actually have a broken lease.
Does bankruptcy disqualify me from renting?
Usually not. Most communities work with discharged bankruptcies (completed, debts cleared). An open Chapter 13 bankruptcy can work too if your payments are current. You’ll still need to meet income requirements and ideally have credit that’s starting to recover.
How long do evictions stay on my record?
Evictions can stay on your screening record for up to 7 years under the Fair Credit Reporting Act. Time does matter: an eviction from 5 years ago gets viewed differently than one from 5 months ago. We track communities for both situations. You don’t have to wait.
What areas in Austin have the most second chance apartments?
North Austin and the Domain area have the highest concentration. Round Rock and Pflugerville have strong inventory. East Austin and Cedar Park/Leander have moderate options. South Austin and Downtown have fewer. It’s not that communities there won’t work with issues; Downtown in particular sets higher credit and income thresholds.
Ready to Find Your Second Chance Apartment?
Here’s what happens next if you want our help: just fill out the form here.
We’ll have a quick conversation, 5 to 10 minutes, where you tell us your situation: credit score, income, any evictions or broken leases, any background issues. We need the full story to help you.
If we can help, we’ll reply within 24 to 48 hours on weekdays with a list of communities whose screening criteria fit your situation. Weekend requests get a reply on Monday. No generic listings, just properties where we track the screening criteria and think you have a real shot.
If your situation is one of the few we don’t have options for, we’ll tell you that too. We’d rather be honest upfront than waste anyone’s time.
No judgment. We’ve heard it all. Just tell us what’s going on, and we’ll figure out your options together.
About Ross Quade
Ross Quade is a licensed Texas REALTOR® and the founder of the Austin Apartment Team. The team helps renters find apartments across the Austin metro, and the service is free to you. (The apartment communities pay the referral fee, not you.)
Ross and the team have toured over 500 properties. They’ve helped hundreds of renters work through this market, from people renting for the first time to people moving from out of state to people with complicated situations. Fill out the short form or call us at (512) 360-0852.
Going to tour on your own? No problem. Just do these 3 things:
- On your tour: Tell them “My apartment locator, Ross Quade, referred me.” Then ask them to note it in your file.
- On your application: Look for the referral field on your application and enter “Ross Quade, Austin Apartment Team.”
- After you apply: Text (512) 865-4672 and let us know where you applied.
That referral costs you nothing, lets us follow up if your application gets stuck, and keeps us in your corner if you need someone to speak up for you.